This post is sponsored by Bank of America but all of the opinions within are those of The Everymom editorial board. We only recommend products we genuinely love.
We Asked Financial Experts How to Raise Money-Smart Kids—Here’s What They Told Us
Teaching kids about money used to be pretty straightforward: Give them a piggy bank, let them count their coins, and toss ’em a few dollars here and there for helping around the house. But raising financially confident kids today comes with a whole new set of questions. When should kids start learning about money? Should they get an allowance? What happens when all their spending is digital? And how do you let them make money mistakes without letting those mistakes get too costly?
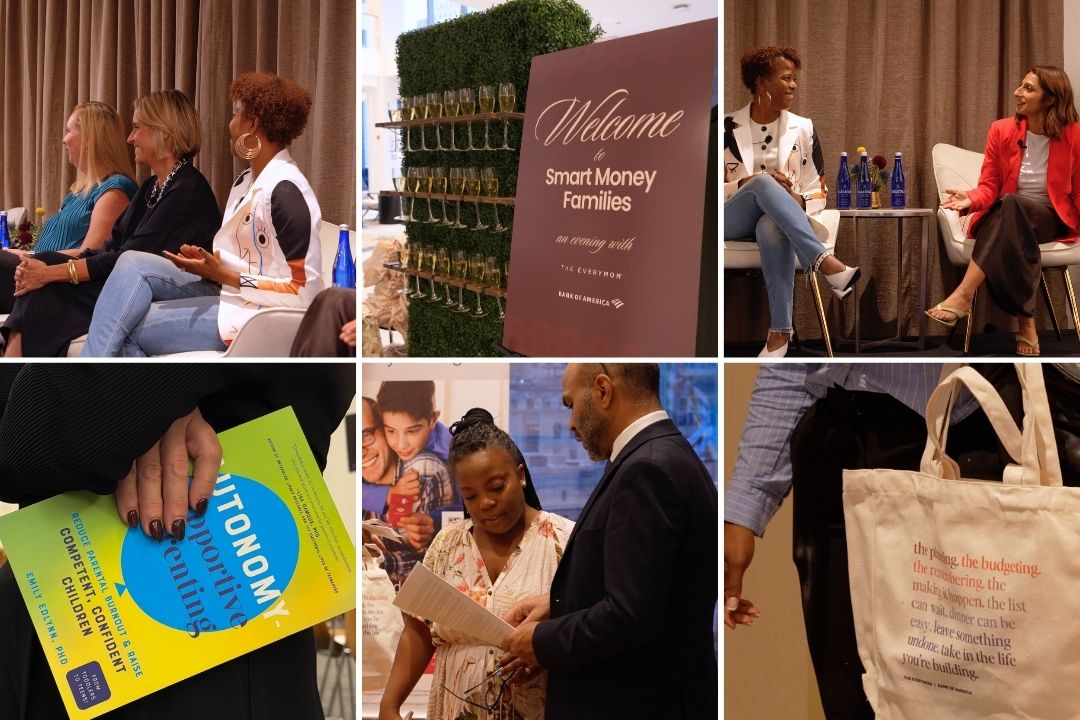
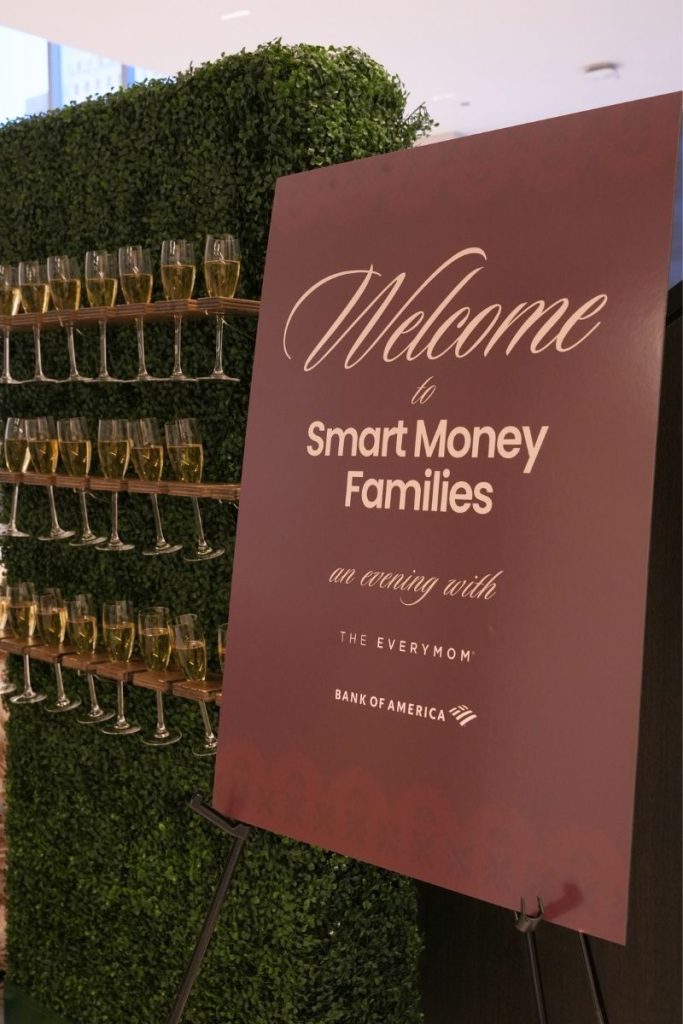
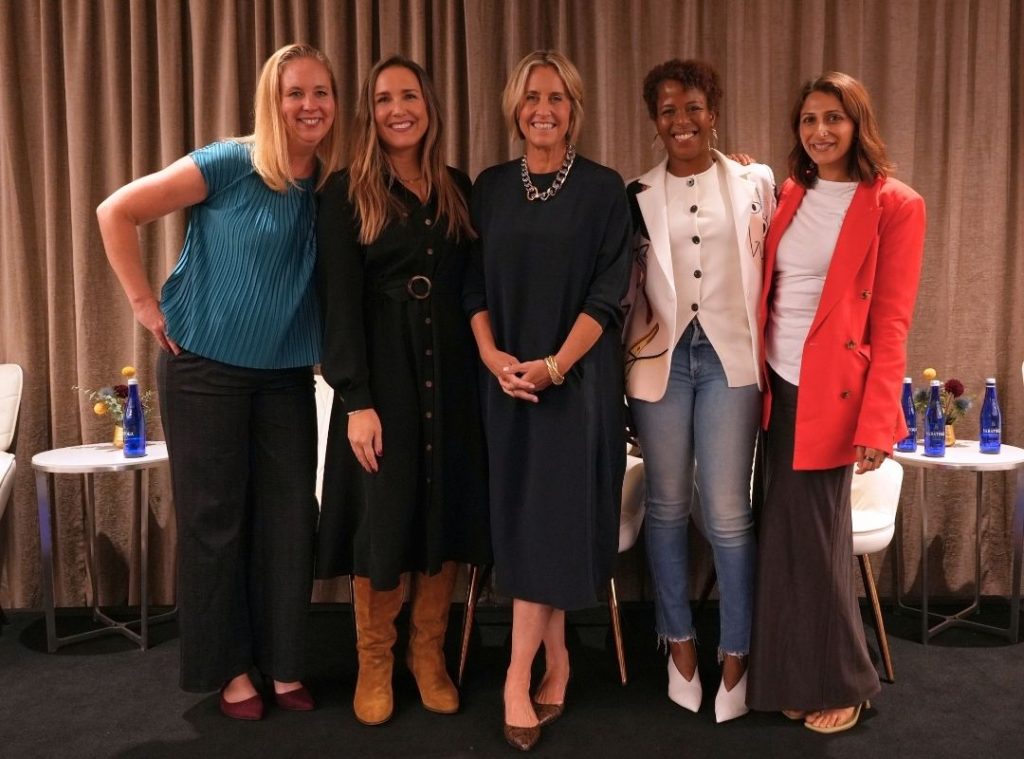
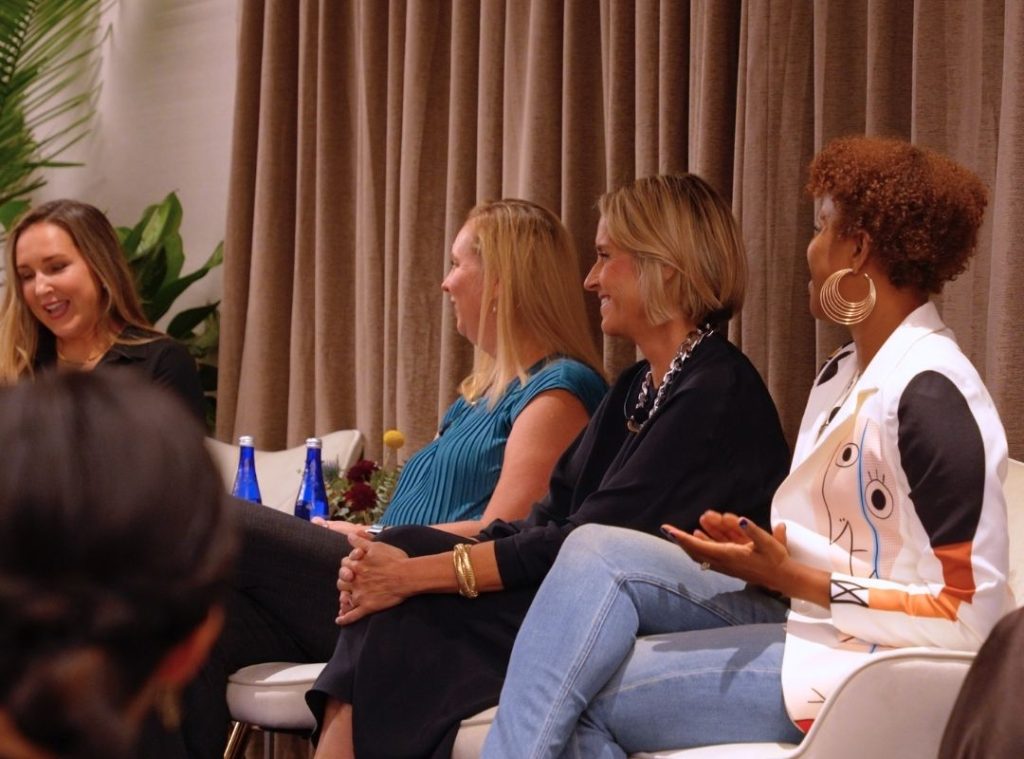
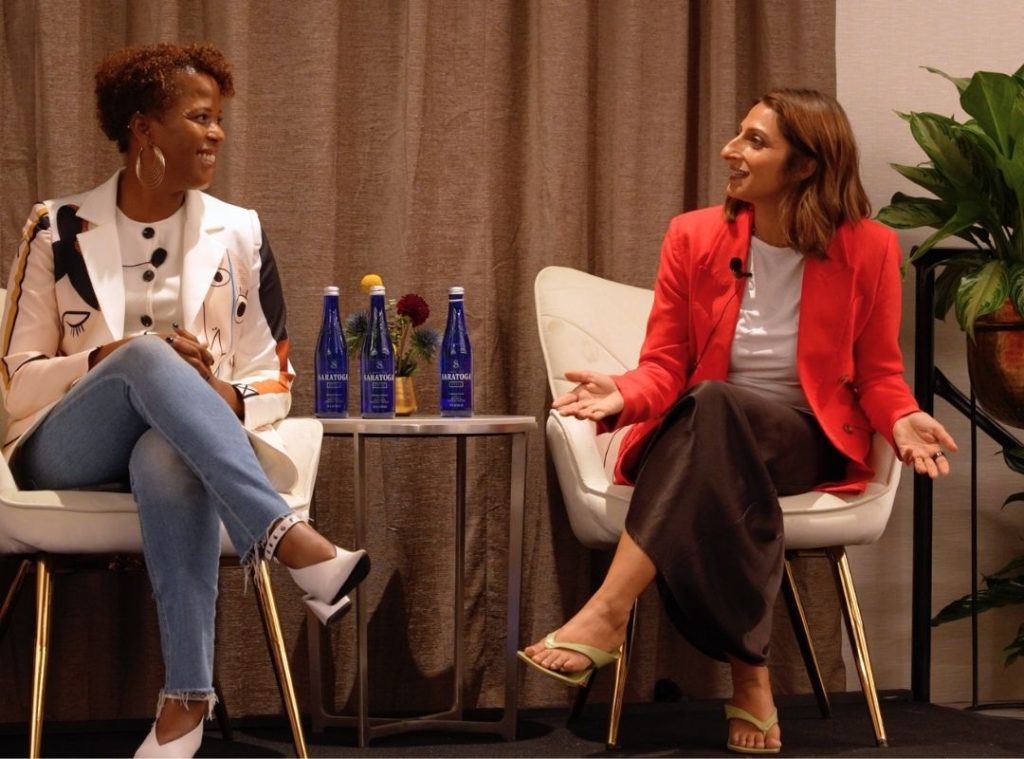
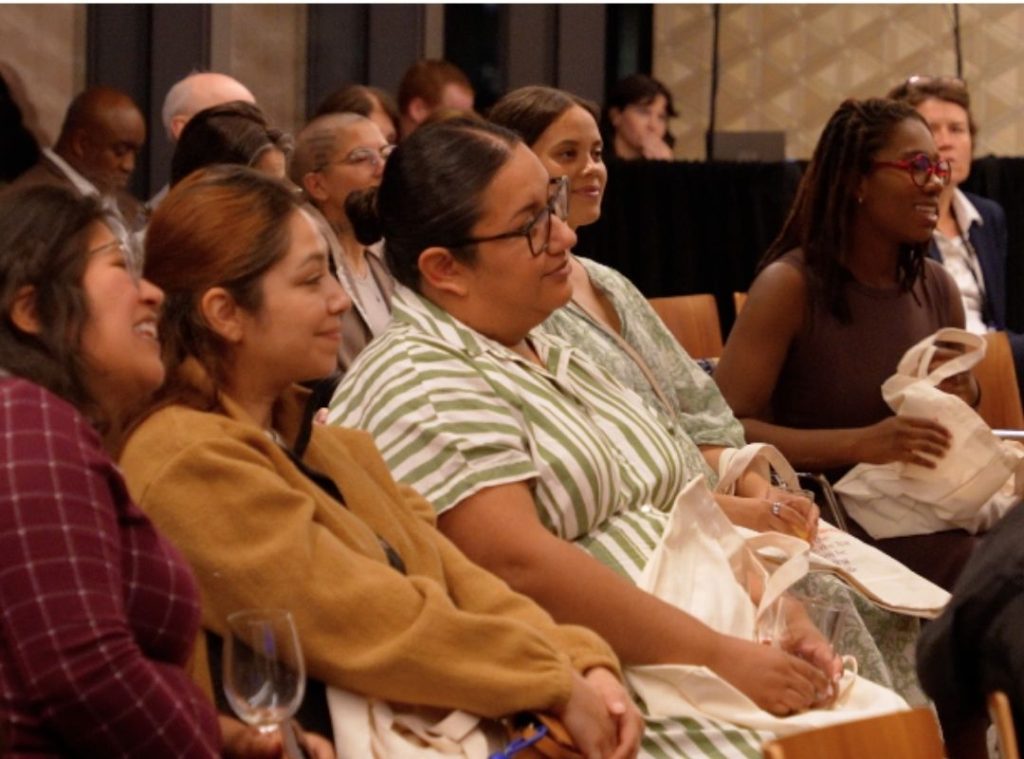
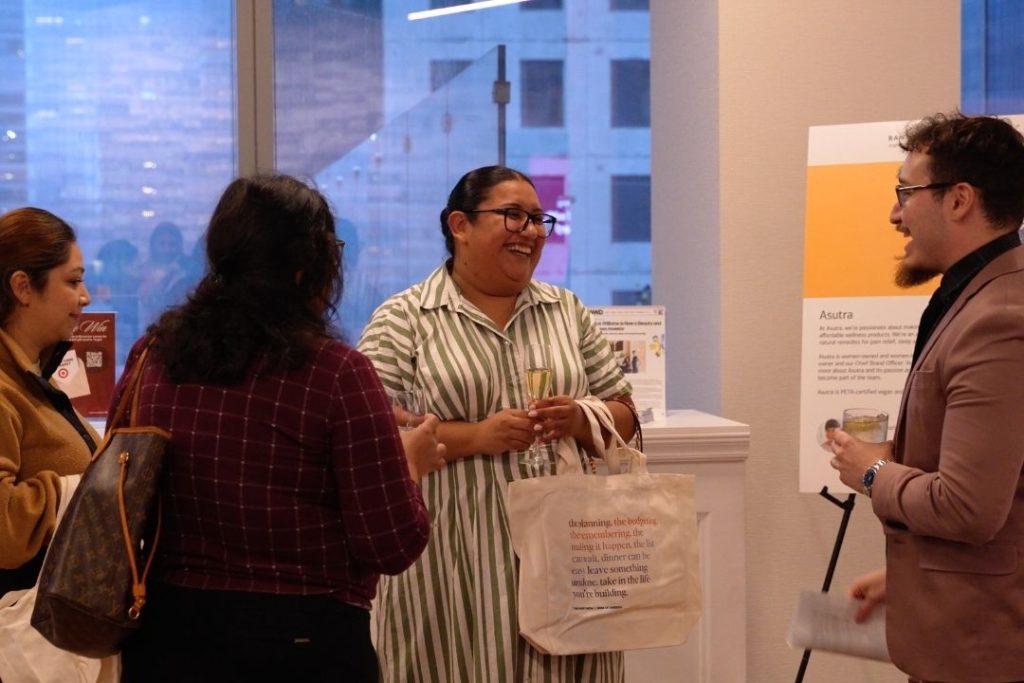
Last week, The Everymom and Bank of America brought together Chicago area-based parents for our Smart Money Families event to talk through exactly those questions. Moderated by our CEO, Alaina Kaczmarski, the conversation featured Holly O’Neill, President of Consumer Banking at Bank of America (and mom of three); clinical psychologist and Autonomy Supportive Parenting author Dr. Emily Edlynn; personal finance expert and Journey to Launch founder Jamila Souffrant; and author, digital creator, and Chicago-area mom of three Jyoti Chand. From allowance and saving to digital banking and impulse purchases, the panel covered a lot—and we left with plenty of advice we’re already thinking about putting into practice.
Your Kids Are Learning About Money From You—Whether You Realize It or Not
Before we can teach our kids about money, we have to reckon with the fact that we’re bringing our own money histories into the conversation. How we grew up, what our parents taught us, and even the things our families didn’t talk about can influence how we approach money with our own kids. For O’Neill, that meant thinking back to her first job scooping ice cream at 14 and the early lesson it taught her about earning and having money of her own. For Souffrant, one of the money lessons that stuck with her came from her mom: “Even if you bring in a dollar, you save a penny.” Dr. Edlynn and Chand also talked about recognizing and moving beyond money mindsets they may have inherited, particularly when it comes to scarcity or anxiety around spending.
This type of self-awareness matters because our kids are picking up on the way we talk about money, too. And thankfully, teaching them about finances doesn’t require a formal sit-down conversation about the stock market. It can start with everyday moments: talking about the difference between something they want and something they need, explaining why you’re choosing to spend money on one thing instead of another, and giving them opportunities to save. As kids get older, those conversations can evolve into budgeting, investing, and more.
The language we use matters, too. Instead of automatically saying, “We can’t afford that,” Dr. Edylnn suggested reframing the conversation around the family’s choices: “We are choosing to spend our family’s money differently.” It’s a small change, but it can help kids understand that money isn’t simply something that’s available or unavailable—families make choices about how to use it.
Allowance Isn’t Really About the Money—It’s About the Practice
Few parenting debates seem to spark as many opinions as whether kids should get paid for chores. The panel didn’t offer one universal answer, but they did offer a helpful distinction: There’s a difference between contributing to your household and earning money. One approach is to keep routine household responsibilities separate from earning, as kids are part of the family, so things like putting away their toys or helping with basic household tasks don’t necessarily need a dollar amount attached to them. Parents can, however, offer opportunities to earn money through additional, non-routine jobs. Souffrant emphasized that kids shouldn’t necessarily be paid simply for participating in family life, while still recognizing that an allowance can give kids actual money to manage—and a safe place to practice making decisions with it. Because a kid can’t exactly learn how to budget if they’ve never had anything to budget.
O’Neill highlighted the value of a simple “spend, save, give” framework, which can help kids start thinking about money as something used fordifferent purposes rather than something that exists solely to be spent. And, as Souffrant pointed out, kids can have insanely different personalities when it comes to money. You might have one child who wants to save every dollar they receive, and another who is already mentally spending theirs before they’ve even gotten it. There’s no need to force them into the same money habits; instead, their natural tendencies can give you clues about where they might need a little more guidance.
As for the allowance question, Dr. Edlynn shared a general guideline of about $0.50 to $1 per week for every year of a child’s age. So, for example, a 6-year-old might receive roughly $3–$6 per week. As kids get older, parents can transition toward opportunities to earn through different kinds of jobs and responsibilities. But ultimately, the exact amount matters less than giving kids an opportunity to make real choices with a manageable amount of money.
Kids Need to Learn How Money Works in the Real World
There’s one pretty major difference between the financial world today’s kids are growing up in, and the one many of us experienced as children: Money isn’t as tangible anymore. It’s pretty easy for a kid to understand that handing over a $5 bill means they no longer have that $5. But tapping a debit card, clicking “Buy Now,” or watching a number on an app change can be much harder for a young kid to conceptualize. That’s why Dr. Edlynn emphasized the value of keeping money concrete for younger children. For kids around 4–6, physical cash, tokens, or other visual representations can help them understand the basic relationship between earning, saving, and spending. As kids get older, digital tools can become part of that education. O’Neill discussed the value of giving older kids visibility into their money through parent-managed accounts and apps so they can actually see their balances change as they spend and save, and how tools like Bank of America’s Family Banking account can give kids real, hands-on experience with money while allowing parents to maintain visibility and guardrails as they build independence.
But understanding digital money is only half the battle. Kids also need to learn how to make thoughtful decisions about spending it. Souffrant shared one simple question she uses to encourage kids to reflect on their purchases: “Was it worth it?” Asking that question after the fact can help kids think about whether something they bought actually brought them the value they expected—and can make the next purchase a little more intentional. Chand shared another strategy for curbing impulse purchases: the 30-day rule. Instead of immediately buying something she wants, she puts it in her notes app and waits. If she still wants it after 30 days, she can revisit the purchase. Obviously, a 30-day waiting period isn’t realistic for every kid or every purchase, but the larger lesson is to give kids opportunities to pause before spending.
And when they inevitably make a purchase they regret? Let them. Dr. Edlynn emphasized the importance of keeping those moments judgment-free. If kids are afraid they’ll be shamed every time they make a bad money decision, they’re much less likely to come to their parents for help when the stakes get higher. A $10 impulse purchase they regret can be a useful learning experience when the alternative is making that same mistake with a much larger amount of money later in life.
If there’s one thing most parents can probably agree on, it’s that giving kids independence is a process. You don’t hand a 10-year-old complete control over their finances and hope for the best—but you also don’t want to be making every financial decision for your 18-year-old. The goal is to gradually shift the balance from parental control toward independence as kids get older. That can mean starting with small decisions: letting a child choose how to spend a few dollars, giving them a budget for a trip to the store, or allowing them to save for something they really want. As they get older, the decisions can get bigger, and the guardrails can loosen up a bit.
And yes, that means kids will make some questionable choices along the way—but that’s kind of the point. Letting a child spend $10 on something they immediately regret gives them a chance to learn about things like opportunity cost, impulse spending, and decision-making while the consequences are still relatively small. Parents also don’t have to make every family’s financial choices look the same. Teaching kids about money can include conversations about your family’s own values and priorities—why you choose to spend money on certain things, why you save for others, and why another family might make completely different choices. The goal isn’t to raise a kid who never makes a bad financial decision. It’s to raise one who understands why they made the decision, can learn from it, and eventually feels confident making those decisions on their own.
Four Things You Can Actually Try This Week
After all the conversations about compound interest, digital banking, allowances, and spending habits, the best part of the event might have been how many of the experts’ suggestions were surprisingly simple. Here are four things you can actually try at home this week with your own kids:
Give them a savings goal: Souffrant recommends helping kids choose something tangible they’re excited to save for, then working together to figure out how they’ll get there. Watching a goal get closer can make saving feel a lot more meaningful than simply being told that saving is “good.”
Give them a budget: Dr. Edlynn suggested giving kids a set amount—$20 at a store, for example—and letting them take ownership of the decision. They might spend it all, save some, or walk away with something they regret buying. That’s all part of the practice.
Let them see their money: O’Neill emphasized the importance of giving kids a way to actually visualize what they’re earning, spending, and saving. As kids get older, digital tools can help make those transactions more concrete while giving parents an opportunity to talk through what’s happening.
Pay attention to who your kid already is: Chand encouraged parents to observe their kids’ natural tendencies around money. Does your child immediately want to spend? Do they carefully save? Do they agonize over every purchase? Those tendencies can give you a starting point for the conversations and boundaries that will be most useful for them.
At the end of the day, raising financially literate kids isn’t about giving them a perfect set of rules. It’s about giving them opportunities to make decisions, ask questions, make small mistakes, and try again. And maybe the best financial lesson we can give our kids is one that doesn’t require a spreadsheet at all: Money is something we can learn how to use—not something we have to be afraid to talk about.
Want to Keep the Money Conversation Going?
Bank of America’s Family Banking account gives kids hands-on experience with saving and spending while giving parents visibility and built-in guardrails as they learn.
McKenna Pringle, Assistant Editor of Branded Content
As the Assistant Editor of Branded Content, McKenna collaborates with our sales team by creating both written and social media content, collecting and analyzing performance data to report back to our partners, and assisting our editors with their everyday tasks to ensure a smooth and productive process.
This post is sponsored by Bank of America but all of the opinions within are those of The Everymom editorial board. We only recommend products we genuinely love.