
At my 3-year-old son’s casual park birthday party on a Wednesday morning, I’m on the playground watching him climb the lower rung of a spiderweb when one of my closest friends steps beside me and confesses, “We’re really struggling financially.”
She’s the second parent to tell me this that day. Earlier that morning, another friend and mom of three told me her husband had just accepted a second full-time job.
“I don’t know when he’s going to sleep,” she admits. “But he says he is already losing sleep over our finances, so at least this way he’ll be earning something.”
On paper, both of these families earn “good money.” But between the high cost of rent, groceries, car payments, and other surprise expenses, they are living paycheck to paycheck.
Even my husband and I, who purchased our home during the recession with a low interest rate, still feel the squeeze. We are far from alone.
Read More:
- Paying for Childcare Is Tough—Readers Reveal How They Make It Work
- 4 Clever Tips for Lowering Your Family’s Grocery Bill
- I Tried a No-Spend Month—Here’s What Surprised Me Most
Parents are paying more for every part of raising a family
Financial pressures on families today are the result of slower wage growth, less affordable housing, and more economic variables, says Sarah Whitmore, ChFC®, financial advisor at Mutual of Omaha.
According to CNBC, prices on everyday items such as groceries, shelter, clothing, health care, and transportation are up around 25 percent since January 2020, more than double the 10 percent inflation seen in the prior five years.
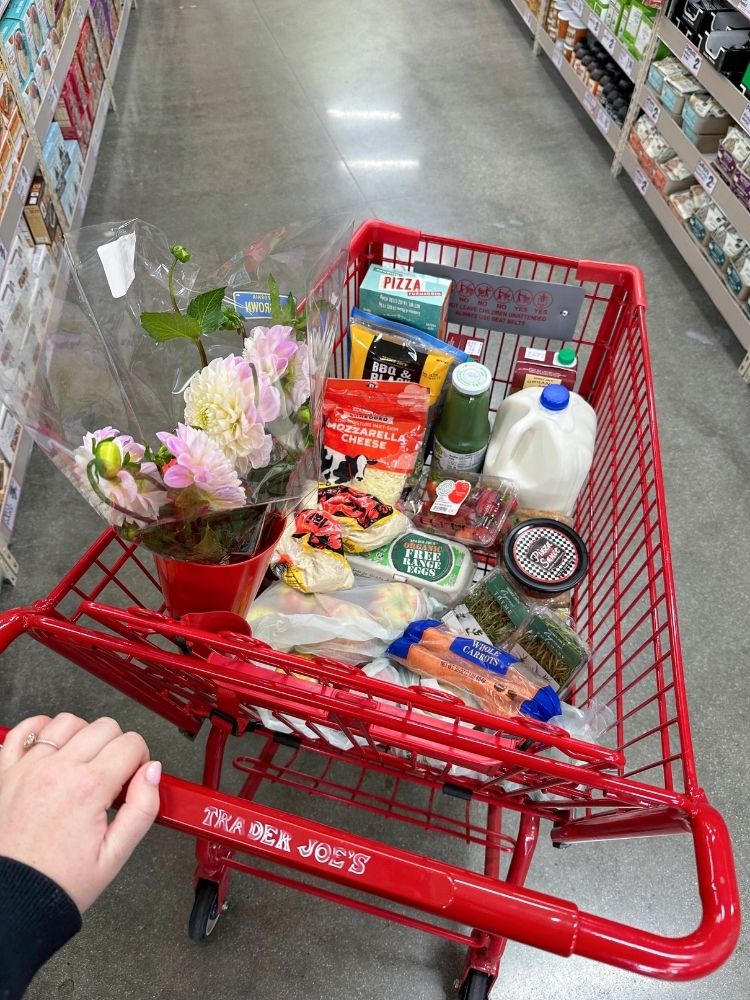
This means that if you spent $100 on groceries in 2019, that same grocery basket would cost you about $124. My own monthly grocery bill has gone up by $500, totaling about $ 1,500 for a family of five. It hurts.
At the time I’m writing this, gas is over $5 a gallon. And childcare costs are at an all-time high. Babycenter surveyed 2,000 parents—76 percent say that paying for childcare strains their family’s budget, while 84% believe the expense prevents them from saving money or paying off debt.
Another study from Care.com found that families spend about 27% of their income on child care, averaging about $17,000. LendingTree estimates that a two-child family would need to earn $400,000 per year to fall within the federal affordability guidelines.
From diapers and formula to school supplies and college prep, the expenses of raising a family are increasing, says Whitmore.
Some parents are going into debt to provide for their kids
National Debt Relief found that six in 10 American parents have gone into debt for their children. Among the 2000 parents surveyed, nearly half say the debt is unmanageable. The average parent in debt owes $14,000 in outstanding credit card debt, while families report an average of $12,000 in medical debt alone.
This has troubling implications. Parents in debt were twice as likely to neglect their physical and mental health—nearly a quarter of parents even admitted to skipping meals sometimes.
Financial experts say many families are in a nasty cycle in which essential costs leave little room for savings, making it difficult to cover emergency expenses like an unexpected dental bill or car repair.
“When all your cash flow is already spoken for, anything else quickly becomes a crisis,” shares Jamie Bosse, CFP®, a financial planner at CGN Advisors and author of Money Boss Mom and Investing for Tweens.
“When all your cash flow is already spoken for, anything else quickly becomes a crisis.”
Parents want to give their kids the world—sometimes at the expense of their own financial well-being
But the squeeze isn’t only coming from inflation. For many families, it’s also intensified by social pressure to give our kids the “best” possible childhood.
Parents feel pressure to overschedule their kids
“It’s no longer enough to keep children safe, loved, and fed,” says Tamara Entina, a Community Health Advisor, Researcher, and Provisional Psychologist. “Today’s perceived standard demands travel, sports, coding bootcamps, private tutoring, and curated after-school portfolios—at a cost that would make previous generations’ heads spin.”
Many worry how they’re going to pay for their kids’ activities
Sixty-two percent of parents with kids in extracurriculars say they’re stressed about how to pay for these expenses, according to another Lending Tree survey. During the summer alone, parents earning $100,000 or more spend an average of $2,123 on seasonal child-related expenses.
“We’ve become a generation of parents running a rat race to close the gap between what we can afford and what the culture tells us our children need,” says Entina.
Choosing to do less can have benefits beyond the family budget
Parents might consider that sometimes the best thing they can do for their kids is to do less and spend less. That might mean rotating activities seasonally instead of committing to year-round sports, prioritizing free play and low-cost family time, or reevaluating whether each activity truly serves your child’s needs.
“It can be hard to put a limit on the things your children are interested in, but the budget always has to be top of mind,” adds Whitmore.
I can relate to this shift firsthand. For a season, I had my daughter on track for a competitive gymnastics team. But ultimately, when they asked us for additional hours that came with an ungodly monthly bill, reshifting our priorities toward family time and free play was the right decision for her and us as a family.
My daughter’s still making gymnastic gains in a more relaxed, once-a-week class, while maintaining her freedom for unstructured play. To me, that’s just as valuable. She’s honestly happier, and so is our wallet.
How families can create more breathing room
Parents often think things would be easier if they just made more money, says Bosse, but making more money often leads to more luxurious or convenient lifestyle choices, making things feel just as tight (AKA lifestyle creep).
What’s perceived as “financially secure” often centers on owning nicer things and taking vacations, but the truth is, says Whitmore, financial security is having at least three to six months of income in savings. Families should fund their savings long before funding vacations.
One main budget leak that families should be aware of is convenience spending, says Bosse, which includes everything from forgotten subscriptions to last-minute delivery fees and impulse purchases.
She suggests automating savings and emergency funds to help parents set aside money before it gets absorbed into monthly spending. Whitmore also encourages regular budget check-ins and putting items on a calendar to visually plan for future, larger expenses or events.
Still, even for families doing everything they can to keep their money in check, inflation and social pressure are making it difficult to stick to a monthly budget. For all of those families struggling right now, that doesn’t mean you’re failing—and you’re certainly not alone.

Kris Ann Valdez, Contributing Writer
Kris Ann Valdez is a mom and freelance journalist who covers parenting, lifestyle, and science-based topics. Beyond The Everymom, Kris Ann contributes to national outlets such as Good Housekeeping, Parents, and Scary Mommy. She’s also the creator of “The Guide Girl,” a Substack dedicated to inspiring writers to pursue publication.
